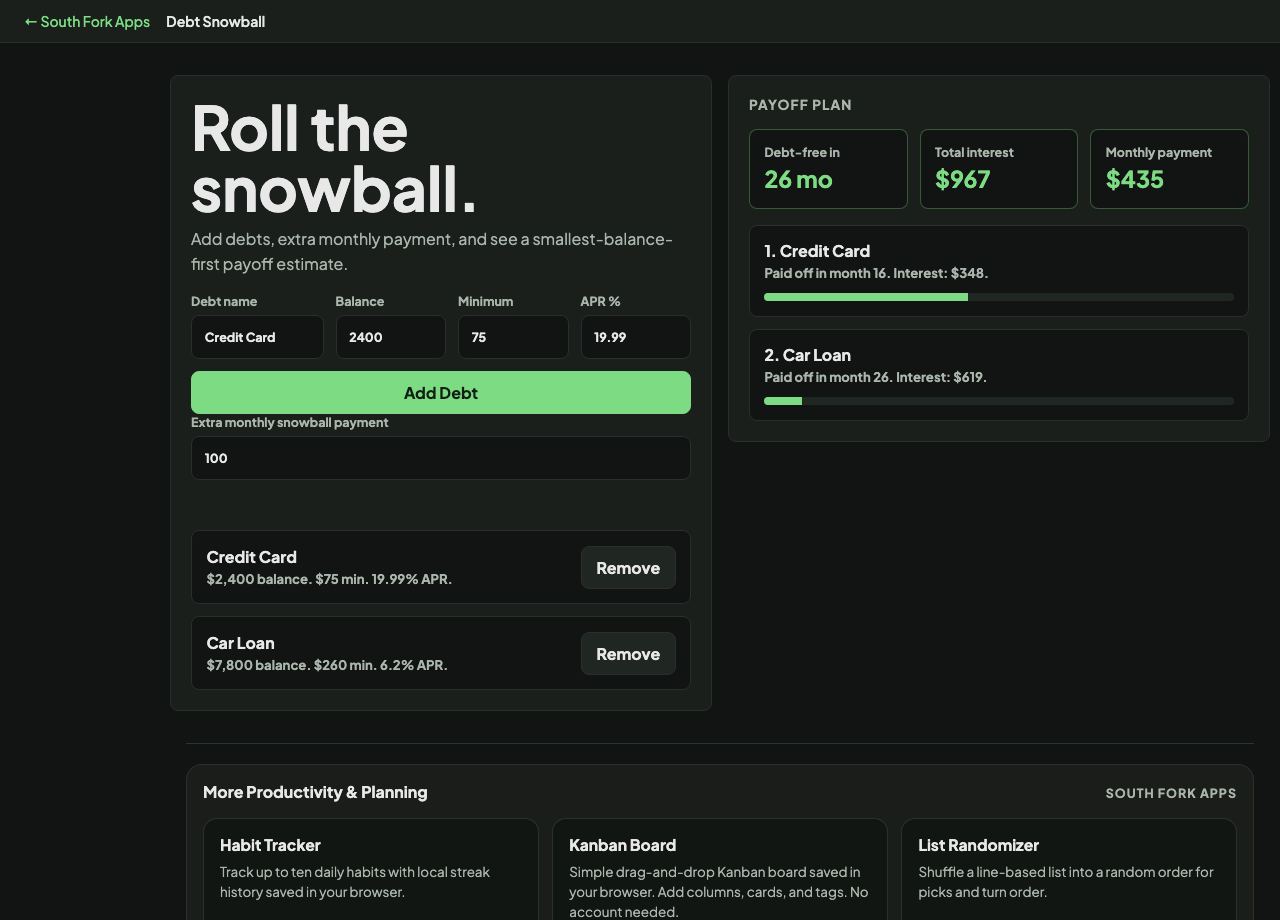
Debt Snowball Calculator
Add debts and an extra monthly payment to see your payoff order and timeline.
Snowball: pay smallest balance first for quick wins.
Debt Snowball Calculator
Debt Snowball Calculator plans a payoff schedule across all your debts, using either the snowball method or the avalanche method, and shows what an extra monthly payment does to your payoff date and total interest.
How to use it
- Add each debt with its name, balance, minimum payment and APR.
- Enter the extra amount you can put toward debt each month.
- Switch between Snowball and Avalanche to compare.
- Read the payoff order, the date, and the total interest for each strategy.
Snowball versus avalanche
Both methods pay the minimum on everything and throw all spare money at one debt. They differ only in which one. Snowball targets the smallest balance first. Avalanche targets the highest interest rate first.
Avalanche always costs less in total interest, sometimes by a lot. Snowball clears individual debts sooner, which produces visible wins early and is why studies of real behaviour find people stick with it more often. The best method is the one you will actually finish, so compare both and be honest about which you will keep doing in month fourteen.
Worked example
The debt the calculator loads with:
- Balance$2,400
- Minimum payment$75
- APR19.99%
- Extra payment$100
Result: Paying $175 instead of $75 clears the card in well under half the time and cuts the interest paid dramatically, because at 20% APR most of a minimum payment is interest.
When it helps
- Choosing between snowball and avalanche with your real numbers instead of arguing about it in the abstract.
- Seeing what an extra $50 a month actually buys in months saved.
- Getting a concrete payoff date rather than an open-ended feeling of debt.
- Deciding which card to attack first.
Common mistakes
- Paying minimums on everything and nothing extra. Minimum payments on a high-APR card are designed to keep the balance alive for years.
- Ignoring the APR entirely. A 6% car loan and a 24% credit card are not the same problem.
- Adding new debt while paying off old debt, which resets the whole plan.
What this tool handles
- A planning tool, not financial advice. Check any consolidation or refinancing offer against these figures before accepting it.