Mortgage Calculator
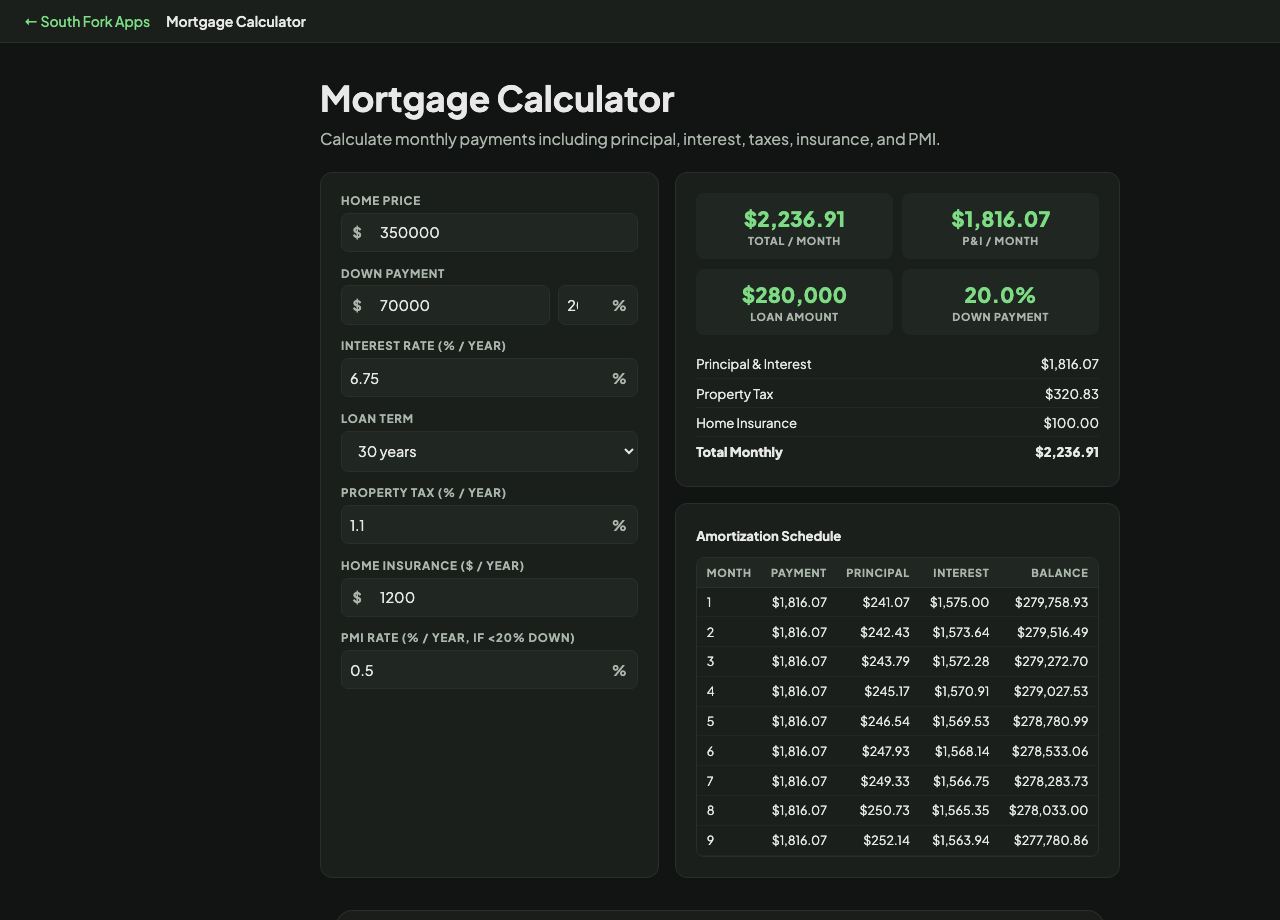
Calculate monthly payments including principal, interest, taxes, insurance, and PMI.
| Month | Payment | Principal | Interest | Balance |
|---|
Mortgage Calculator
Mortgage Calculator estimates a full monthly housing payment, not just principal and interest. It folds in property tax, home insurance, and PMI, then shows the amortization schedule so you can see how the split between interest and principal changes over the life of the loan.
How to use it
- Enter the home price and your down payment. The dollar and percentage fields stay in sync, so you can drive it from either one.
- Set the interest rate and pick a term: 30, 15, 10, or 7 years.
- Adjust the property tax rate, annual insurance, and PMI rate if you know your real numbers.
- Read the monthly payment breakdown and scroll the amortization schedule.
The amortization formula
Principal and interest come from the standard amortizing loan formula: M = P x r x (1 + r)^n / ((1 + r)^n - 1), where P is the amount borrowed, r is the monthly interest rate (the annual rate divided by 12), and n is the number of monthly payments.
Property tax and insurance are annual figures divided by 12 and added on. PMI is charged as a percentage of the loan amount per year and only applies while the down payment is under 20%, which is why it disappears from the total the moment you cross that line.
Worked example
Using the values the calculator loads with:
- Home price$350,000
- Down payment$70,000 (20%)
- Interest rate6.75%
- Term30 years
- Property tax1.1% / year
- Insurance$1,200 / year
Result: Borrowing $280,000 gives roughly $1,816 a month in principal and interest, plus about $321 in tax and $100 in insurance, for a total near $2,237. At 20% down there is no PMI.
When it helps
- Checking what a listing price actually costs per month before you tour the house.
- Comparing a 30-year and a 15-year term on the same loan to see the real trade between payment size and total interest.
- Working out how much extra down payment it takes to clear 20% and drop PMI.
- Sanity-checking a lender's quote against an independent calculation.
Common mistakes
- Budgeting on principal and interest alone. Tax and insurance often add several hundred dollars a month and are usually collected in the same payment through escrow.
- Assuming PMI is permanent. It normally falls away once you have 20% equity, which happens sooner if home values rise.
- Using the advertised rate instead of your quoted rate. Advertised rates usually assume excellent credit and discount points.
What this tool handles
- The down payment dollar and percent fields update each other, so changing one corrects the other.
- PMI is applied only when the down payment is below 20%.
- The amortization schedule shows every month, so you can see the exact point where you start paying more principal than interest.